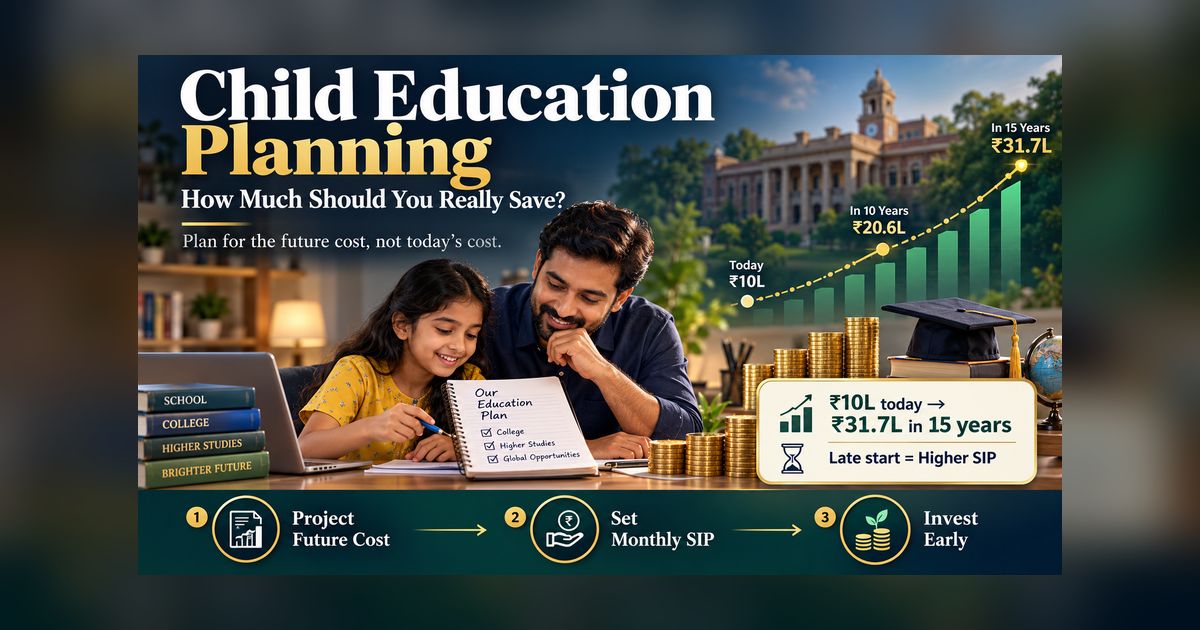
Child Education Planning: How Much Should You Really Save?
Education costs
in India have historically tended to rise faster than general consumer
inflation. [Verification required — cite a specific, dated figure before
publishing.] That means the number you have in mind today for your child's
education is very likely too small for the year they'll actually need it.
Plan for the
future cost, not the current one.
Step 1: Define
the Goal Precisely
"Save for my
child's education" is too vague. You need: which stage (school,
undergraduate, postgraduate, abroad), which course type, and how many years
away.
Step 2: Project
the Future Cost
Illustrative
example: An engineering degree costing ₹10,00,000 today, projected at an assumed 8% annual education-inflation rate, comes
to roughly ₹31,70,000 in 15 years — about three times today's figure.
Step 3:
Reverse-Calculate the Monthly SIP
Illustrative
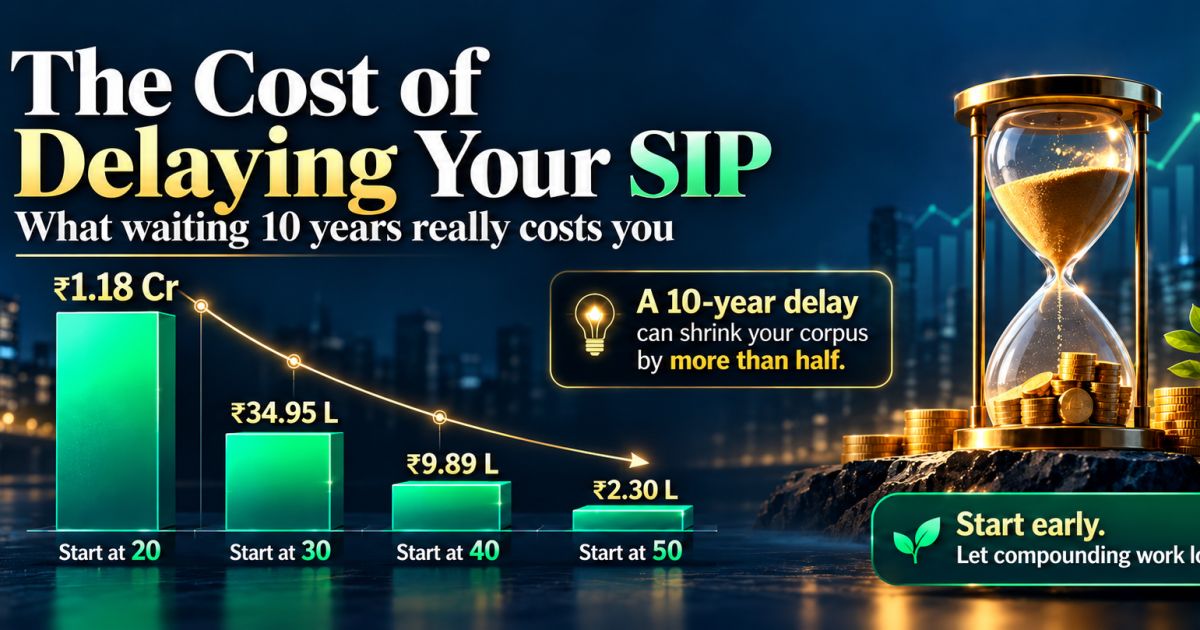
scenario: To reach ~₹31,70,000 in 15 years at an assumed 12% return, the required SIP is roughly ₹7,500–₹8,000/month. Starting five years later, with only 10 years
left, needs a substantially higher monthly amount for the same target — a
direct example of the cost of delaying your SIP.
(Figures are
illustrative only and depend on your specific cost estimate, inflation
assumption, and horizon.)
Matching
Allocation to Time Left
- 10+ years to goal: typically allows for higher equity allocation
- 5–10 years: often a hybrid approach, shifting gradually toward
debt
- Under 5 years: usually calls for a more conservative, debt-heavy
mix to protect the corpus right before it's needed
See our asset
allocation guide for the fuller framework.
Frequently Asked
Questions
How much should I save monthly for my
child's education?
It depends on
your child's age, the education type, and your return assumption — a goal-based
calculation projecting the future cost gives a far more accurate number than a
generic figure.
Is education inflation
really higher than regular inflation?
It has
historically tended to be, though the exact rate varies by institution and
course type. [Verification required for a current, dated figure.]
What if I'm starting
late?
It's still worth
planning — the required monthly investment will simply be higher for the same
target and timeline. Starting today beats delaying further.
The Bottom Line
The single
biggest planning error is using today's cost instead of the projected one. Run
the projection first — it changes the monthly number significantly.
Would you like to
understand how this applies to your financial goals? Connect with Vikalpa
Finvest for a structured discussion about your goals, investment horizon, risk
profile and existing portfolio.
Call: 98240 40666 | Email: mf@ashokindia.com
Disclaimer: Mutual fund investments are subject to market risks. Read all scheme-related documents carefully. Calculations and assumed returns are for illustration and educational purposes only. Actual returns may vary and are not guaranteed.